Should You Sell Your Home Before Buying Your Next One in Marin?
Should you sell before buying in Marin? It is the question I hear at almost every kitchen table in Marin County: "Corey, do we sell first or buy first?" Get it right and you move once, on your timeline, with your equity working for you. Get it wrong and you are either carrying two mortgages or living in a storage unit with your golden retriever.
Here is the honest answer. There is no universal right move. There is only the right move for your equity, your nerves and this specific Marin market. So let's look at the market first, then the playbook.
The Marin market right now: great for sellers, tough for contingent buyers
Marin is the tightest single-family market in the North Bay. In August 2026, the median single-family home in Marin County sold for $1,778,000, up 15.83% from a year earlier, and homes went under contract in a median of just 21 days. Inventory sat at 2.0 months of supply, the tightest reading in three years. Anything under three months is a seller's market.
At the same time, money got more expensive. The 30-year fixed rate averaged 7.28% on October 1, 2026, its highest level since early 2025.
What does that combination mean for you as a move-up buyer or downsizer?
-
Selling your current home should be the easy part. Well-prepared Marin homes are moving fast.
-
Buying your next home is the hard part. With so few listings, the home you want will likely see multiple offers. A sale-contingent offer is the weakest offer on the table.
-
Your equity is your superpower. Many Marin owners are sitting on years of appreciation. The question is how to unlock it before you need it.
Option 1: Sell first
Selling first is the conservative play. You know exactly what you netted, you shop with real numbers, and you write clean, non-contingent offers that sellers take seriously.
The catch is the gap. Where do you live between closing and finding the next home?
-
Negotiate a rent-back. In a seller's market like Marin, buyers will often let you stay 30 to 60 days after closing. That gives you a runway to shop with cash in hand.
-
Line up a short-term rental. Furnished rentals in Marin are not cheap, but a few months of rent is often less than the cost of losing your dream home to a stronger offer.
-
Extend your escrow. A 45 to 60 day close on your sale buys you time to find and win the next home.
Best for: owners who need their equity for the down payment, anyone who cannot qualify for two payments, and anyone who sleeps better with certainty.
Option 2: Buy first
Buying first means you move once, on your schedule, and you can prep and stage your current home after it is empty. Empty, staged homes in Marin photograph better and sell faster.
The catch is carrying cost. At today's rates, owning two Marin homes for even two or three months is real money.
Ways to make it work:
-
Bridge loan. A short-term loan against your current home's equity that funds your next down payment. Higher rates and fees, but it lets you write a non-contingent offer.
-
HELOC. Open a home equity line of credit before you list. Note that most lenders will not open one on a home that is already on the market.
-
Buy-before-you-sell programs. Several lenders and companies now offer programs that back your purchase with your current home's equity. Read the fee structure closely.
-
Cash or securities-based lending. If you have the liquidity, this is the strongest position in the market.
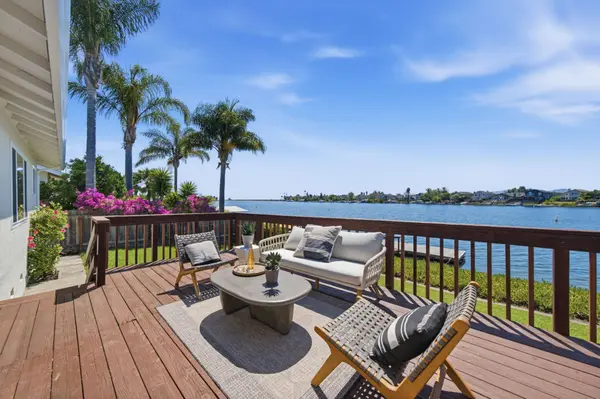
Best for: buyers with strong income and equity, and anyone chasing a specific home or a specific street, like a deep-water lot in Bel Marin Keys, where the right house might hit the market once a year.
Option 3: Make a contingent offer
A home sale contingency lets you buy subject to selling your current home. It protects you, but it asks the seller to take on your risk. In a 2.0-month supply market, most Marin sellers with multiple offers will pass.
It can still work when a home has been sitting, when your home is already in contract, or when your agent has a relationship with the listing agent and can show that your home will sell fast. Context matters, and that is where local knowledge earns its fee.
The Marin factor most people miss: Prop 19
If you or your spouse is 55 or older, California's Proposition 19 may let you take your current property tax base with you. The replacement home can be anywhere in California, of any value, and you can use the transfer up to three times. If the new home costs more than the one you sold, the difference is added to your tax base.
The key rule for this decision: the purchase must happen within two years before or after the sale. That means you can buy first or sell first and still qualify, as long as you stay inside the window. For a long-time Marin owner, that can be worth thousands of dollars a year. Always confirm the details with the Marin County Assessor and your tax professional.
My framework: three questions
When I sit down with clients, we answer these first:
-
Do you need the equity from your current home to buy the next one? If yes, you are likely selling first or using a bridge product.
-
Can you comfortably carry two payments for 90 days? If not, sell first.
-
How rare is the home you want? If it is a once-a-year waterfront listing, buy first and protect your shot. This goes for areas in Southern Marin like Mill Valley, which are super hot markets right now.
Answer those honestly and the strategy usually picks itself.
Frequently asked questions
Can I make a contingent offer in Marin right now? You can, but expect it to lose to non-contingent offers on most well-priced homes. It works best on listings with longer days on market. This likely wouldn't fly in Mill Valley or Sausalito right now, but there could be some options in San Rafael and Novato.
How does a rent-back work? You sell and close, then rent your home back from the buyer for an agreed period, usually 30 to 60 days, under a written agreement.
Can I keep my low property tax if I move? If you are 55 or older, Prop 19 may let you transfer your tax base to a replacement home bought within two years of the sale. It's best to be speaking with a tax advisor or CPA while making these big life decisions.
What does capital gains look like when I sell? Federal rules currently exclude up to $250,000 of gain for single filers and $500,000 for married couples on a primary residence. Long-time Marin owners can exceed that, so talk to your CPA before you list.
Let's build your move-up plan
Every sell-first or buy-first decision starts with two numbers: what your home will sell for, and what you can buy with it. I will run both for you, connect you with lenders who do bridge and HELOC financing every day, and map out a timeline that gets you moved once.
Call or text me at 415-858-9469, or start with a free home valuation at belmarinkeysre.com. The right sequence makes all the difference. The Road Best Traveled!
Market figures: Marin County single-family data for August 2026 via Mosaik Real Estate's North Bay report. Mortgage rate via Freddie Mac PMMS, October 1, 2026. This article is general information, not legal, tax or lending advice.
Corey Robinson | Journey Real Estate | DRE #01783258
Categories
Recent Posts